Payment Methods for Small Businesses: What to Offer, What It Costs, and How to Choose
Choosing the right payment methods for small business owners is no longer just a question of having a till and a card machine. Customers arrive expecting to pay in the way that suits them, and if that way is not available, some will simply buy elsewhere. At the same time, every method you offer has a cost, a delay before the money reaches your account, and a set of risks to manage. This guide walks through the main options in plain language, explains what each one really costs, and helps you match your payment mix to the kind of business you run.
The goal is not to offer every possible method. The goal is to offer the methods your customers actually use, at a total cost you understand, with settlement times that support your cash flow rather than strain it.
The Main Ways Customers Can Pay
Cash
Cash is immediate, familiar and free of processing fees at the point of sale. Once a note is in your till, the sale is complete and there is no waiting for a provider to release funds. The costs sit elsewhere: counting, storing and banking cash takes staff time, carrying it to the bank carries risk, and mistakes or losses are hard to trace. Cash also needs change, floats and safe storage, which we cover in more detail in our other guides.
Card Payments: Chip, PIN and Contactless
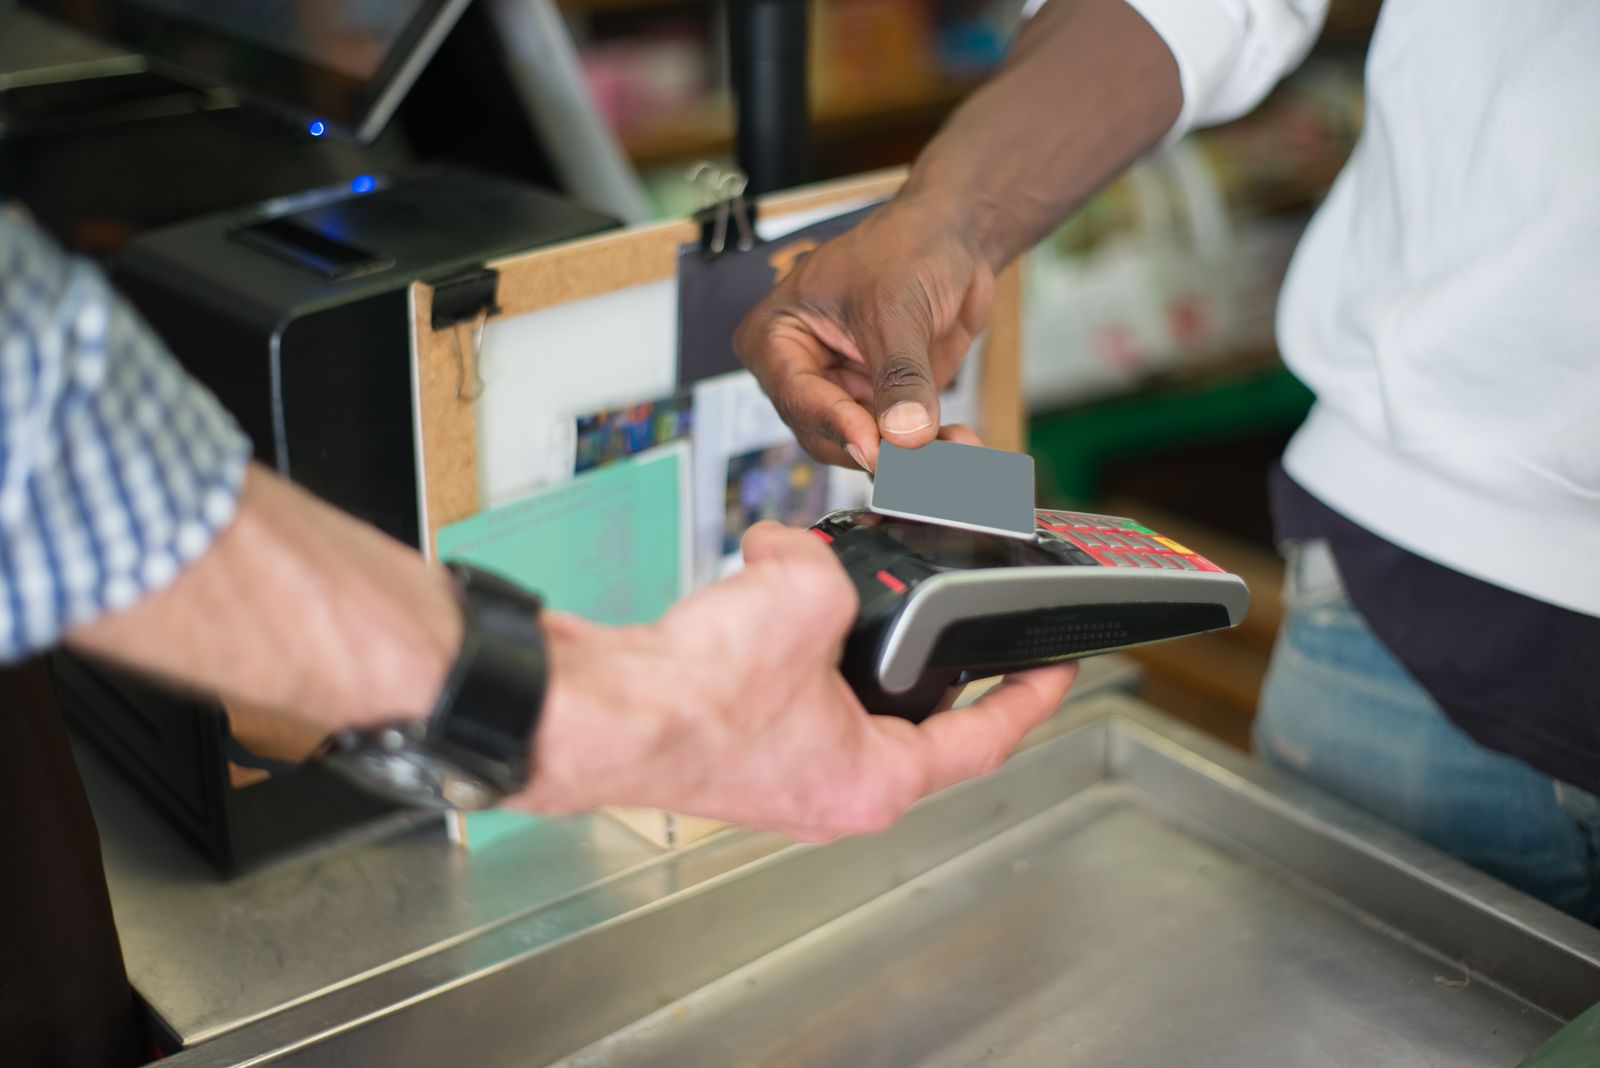
Debit and credit cards remain the workhorse for most shops, cafes and face-to-face businesses. A customer inserts a card and enters a PIN, or taps for a contactless payment. Card acceptance requires a terminal or card reader from a payment provider, and each transaction carries processing charges. In return, payments are recorded automatically, refunds are traceable, and the money moves to your bank account without a trip to a branch.
Mobile Wallets
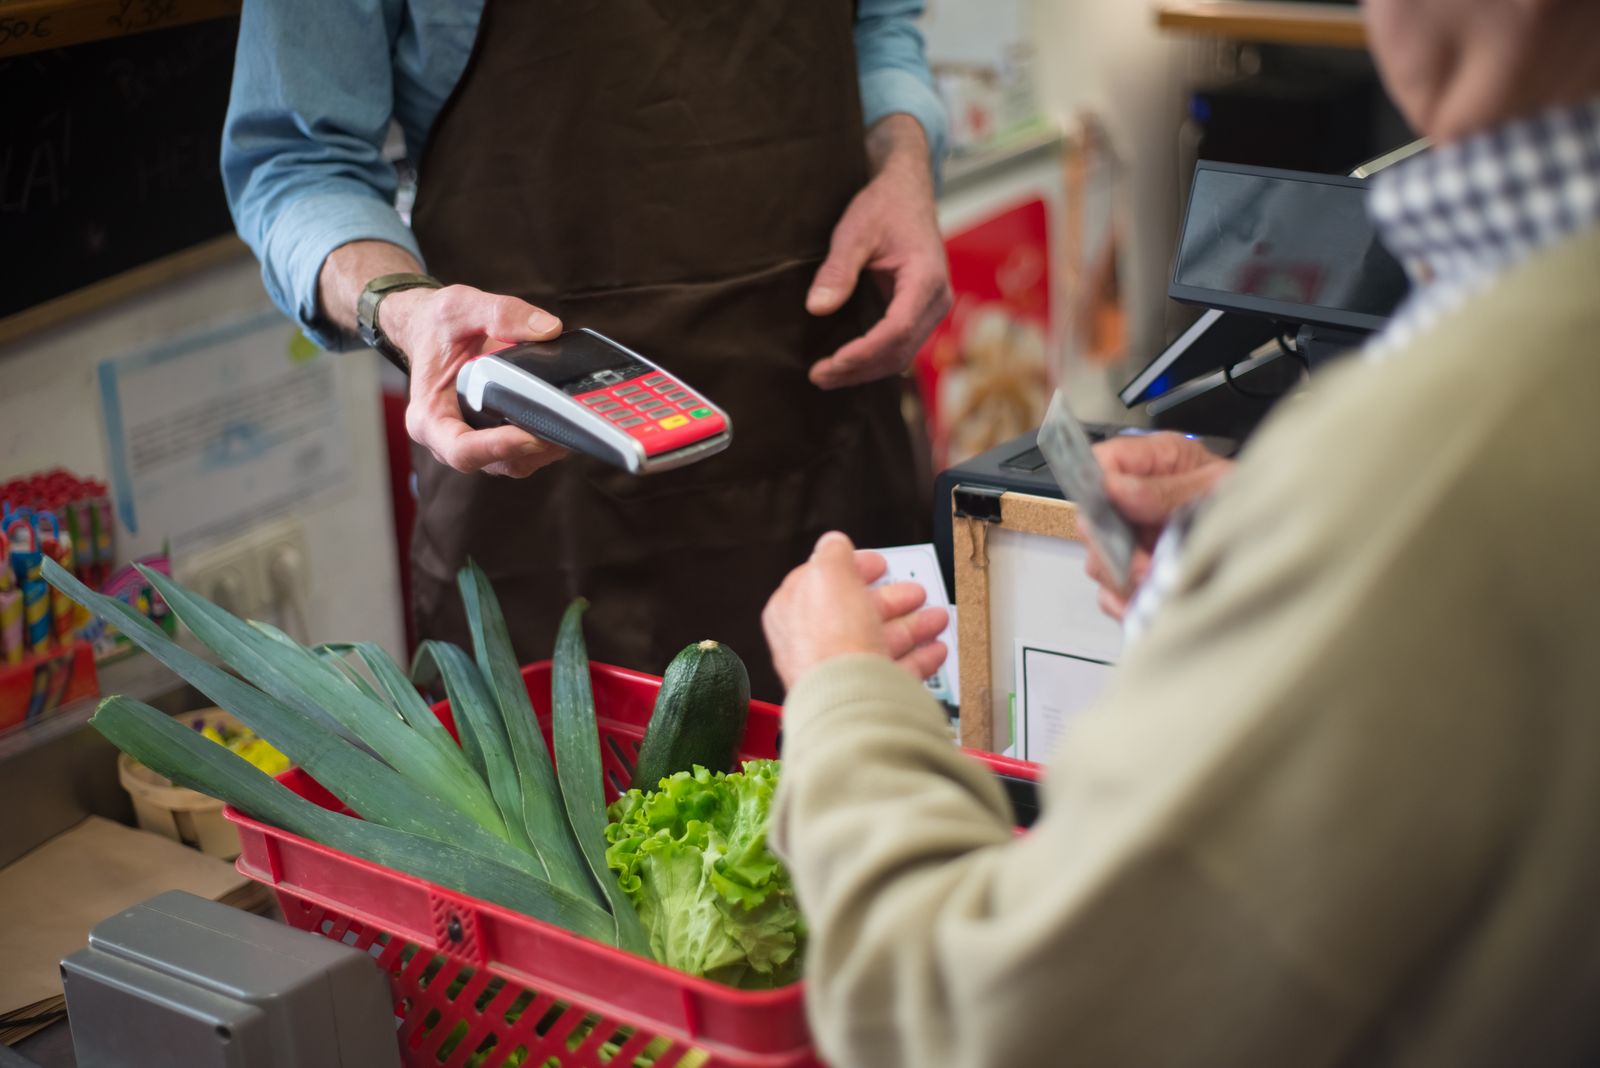
Mobile wallets let customers pay with a phone or smartwatch instead of a physical card. The payment runs over the same card networks, usually through the same terminal you already use, so for many businesses there is nothing extra to install. Customers like the speed, and the built-in phone security, such as fingerprint or face checks, adds a layer of protection to each sale.
Bank Transfer and ACH Payments
Bank transfers move money directly from the customer’s bank account to yours. They are well suited to larger invoices, regular clients and business-to-business work, where card fees on a big amount would be painful. The trade-off is speed and certainty: transfers may not arrive instantly, references can be typed incorrectly, and you need a habit of checking your account and matching payments to invoices.
Payment Links and Online Invoices
Payment links let you send a secure page by email, text or messaging app where the customer pays by card or wallet without you handling their details. Online invoicing tools do the same job attached to a numbered invoice. These methods are ideal for tradespeople, consultants and service businesses that are not standing in front of the customer when the bill is due.
Buy Now, Pay Later
Buy-now-pay-later services let a customer split a purchase into instalments while the business is paid by the provider, usually after a fee. It can suit higher-value retail, but it is not right for every business. Read the provider terms carefully, understand who carries the risk if a customer does not pay, and consider whether encouraging instalments fits the products you sell.
What Each Method Really Costs
Fees vary by provider, by country and by the type of card or transaction, so treat any headline rate as a starting point rather than the full picture. When you compare providers, look at the total cost of accepting payments, not a single advertised percentage.
- Transaction charges: most card and wallet payments carry a percentage of the sale value, sometimes plus a small fixed amount per transaction.
- Equipment costs: terminals may be bought outright, rented monthly, or included in a package. Ask what happens if a reader breaks.
- Monthly and account fees: some providers charge a standing fee, statement fees or minimum monthly charges, while others charge nothing fixed and earn only from transactions.
- Chargeback and refund costs: disputed card payments can trigger extra fees and take staff time to answer, so factor them into comparisons.
- Your own time: cash handling, banking trips and reconciling transfers all consume paid hours. A method that looks cheap on paper can be expensive in practice.
Before signing, ask each provider for a clear written summary of every charge that could apply to your business, how long the contract runs, what notice you must give to leave, and when fees can change. A trustworthy provider will answer those questions in writing without pressure.
Settlement Speed and Your Cash Flow
A sale is not the same as money in the bank. Card and wallet payments typically settle after a delay set by your provider, transfers depend on banking hours and processing, and cash is available immediately but only becomes useful once it is safely banked. Slow settlement can leave a busy business short of funds for wages, rent or supplier bills even while sales look healthy.
This is why payment choices belong in your wider cash planning. If you are working through practical steps to improve cash flow management, note the typical settlement day for each method you accept, and reflect those days honestly when you build a simple 13-week cash flow forecast. A forecast that assumes same-day access to card takings will mislead you if your provider pays out later in the week.
What Customers Now Expect
Expectations differ by sector, but some patterns are now widespread. Shoppers generally expect contactless card and phone payments at any counter, clear prices with no surprise charges added at the till, and a receipt in the format they prefer. Service customers increasingly expect to pay an invoice online rather than write a cheque or visit in person. Business clients often expect bank transfer details on the invoice itself.
You do not need to chase every new option, but you should know which methods your own customers ask for. Keep a simple note of requests and abandoned sales for a few weeks. That evidence is worth more than any sales pitch when you decide what to add.
Fraud and Security Hygiene for Each Method
- Cash: use clear counting and storage routines, keep floats modest, and bank takings regularly rather than letting cash build up on site.
- Cards: never write down card numbers, use the provider’s approved terminal, keep its software updated, and train staff to follow the terminal prompts instead of bypassing security checks.
- Mobile wallets: rely on the terminal and provider you already trust, and keep devices that accept payments locked with strong passcodes.
- Bank transfers: warn regular customers to check bank details carefully, confirm any change of details by a separate channel, and match every incoming payment to an invoice before releasing goods.
- Payment links: send links only through your official invoicing system, and remind customers that you will never ask them to pay into a personal account.
- Buy now, pay later: use the provider’s checkout exactly as designed and never record a customer’s instalment details yourself.
How to Choose by Business Type
Retail and Hospitality Counters
Prioritise fast card, contactless and wallet payments, with cash accepted and handled under a clear routine. Speed at the till protects your queue, and automatic records simplify the end-of-day reconciliation.
Services and Invoicing Businesses
Lead with bank transfer and payment links attached to clear, numbered invoices. Offer card payment for clients who prefer it, and state your payment terms and details on every invoice so there is no friction about how to pay.
Selling Online
Use a recognised checkout that accepts cards and wallets, shows the total price early, and emails automatic receipts. Review abandoned checkouts: if customers leave at the payment step, the problem is often choice or trust, not price.
Common Mistakes to Avoid
- Offering too few options: a single method forces customers into your preference instead of theirs, and some sales will quietly disappear.
- Hiding fees: adding surprise charges at the till damages trust and may breach local rules. Price honestly and absorb or disclose costs transparently.
- Ignoring settlement times: choosing a provider on fees alone, then discovering payouts arrive later than your bills, creates avoidable cash pressure.
- Never reviewing the contract: volumes and prices change. Recompare your total cost each year against your actual transaction mix.
Watch the short video below for a helpful overview of payment methods and processors for small businesses.
Frequently Asked Questions
What is the best payment method for a small business?
There is rarely a single best method. Most businesses do well with a small, deliberate mix: cards and wallets for face-to-face sales, bank transfer or payment links for invoices, and cash handled under a secure routine where customers still use it.
How much do card payments cost a business?
Costs vary by provider, card type and contract, and may include transaction charges, terminal costs and account fees. Compare the total monthly cost based on your real sales pattern rather than relying on a single advertised rate.
How quickly will I receive card payments?
Settlement timing is set by your provider and your bank, and it differs between providers. Ask for the expected payout schedule in writing before you sign, and build that timing into your cash flow forecast.
Should I stop accepting cash?
That depends on your customers. Some still rely on cash, and removing it can exclude them. Many businesses keep cash but handle it with strict counting, storage and banking routines to control the risk and effort involved.
Is buy now, pay later suitable for my business?
It can suit higher-value purchases where customers value spreading the cost, but it is not essential for most everyday sales. Read the fees, responsibilities and terms carefully, and consider whether it fits your products and customers before adding it.
A Sensible Next Step
Start by listing how your customers paid you over the last month, what each method cost you in fees and time, and how long each took to reach your bank account. That one-page picture usually shows exactly where to act first. If you would like a second pair of eyes on the numbers, BCC Financial Management Services can help you review your routine and plan practical improvements at your own pace, with no obligation to change providers.
Disclaimer: This article is general educational information only and is not financial advice. Consider your own circumstances and seek professional advice where appropriate.